Taxes explained
Taxes fund schools, roads, hospitals, and safety services. In the United States, most people pay federal taxes and state taxes. The tax year runs January 1 to December 31 for reporting income. Your income tax bill depends on earnings and the credits or deductions you claim. 🧾
Key terms you’ll see during tax season include the tax return, tax form like the 1040, and the tax documents you gather from employers or banks. If you withhold too much from each paycheck, you’ll get a tax refund. If you withhold too little, you’ll owe balance due when you file. 🧾💡
Many filers use a tax preparation service or a tax preparer to help complete forms, and you can file for free in some cases. Always note important tax deadlines to avoid penalties for late filing or payment. ⏰
- Real-world example: A single filer in 2024 earned $60,000, paid $4,500 in federal withholding, and qualified for a $1,500 standard deduction. Their refund or liability depends on the exact figures from the 1040 line items.
- Practical step: Gather W-2s, 1099s, and receipts for deductible expenses before starting your return to save time. 🗂️
- Tip: If you’re near a filing deadline, use free tax software or IRS Free File options to avoid paying for basic filing. 🧭
What taxes and its importance
Taxes fund essential services like schools, roads, and public safety. They come from two main sources: federal taxes and state taxes, with local taxes adding others. Knowing how they work helps you plan money and avoid surprises during tax season 🧾. Here’s a practical, real world breakdown with steps you can take this year.
Key ideas to keep in mind include:
- Income tax is based on earnings and can vary by filing status and credits. For example, a single filer earning $60,000 pays a different rate than a married couple earning $120,000 combined, influencing their 2025 tax return.
- There are tax credits and deduction options that reduce what you owe. Common ones include the child tax credit, education credits, and the standard vs itemized deduction choice.
Why it matters in real life:
- Missed deadlines can trigger penalties and interest on tax payments or the tax bill from both federal and state authorities. A $500 balance due today can grow to over $600 with penalties if you delay two months, impacting your ability to receive your refund.
- Understanding whether you file as married filing jointly or separately Affects your liability and credits like the earned income tax credit, which can lead to a refund advance loan. earned income tax credit or the child tax credit. For some households, filing separately reduces phaseouts for credits but increases tax on certain income types.
Connecticut tax overview
Connecticut taxes come from both federal income tax and state taxes. The state relies on personal income tax, sales tax, and local property taxes, with rules that differ for residents and part year residents. 🧾
Key points to know:
- State income tax is administered by the Connecticut Department of Revenue Services and uses brackets that change by filing status.
- Most residents file a state tax return along with the federal return to report income, deductions, and credits.
- Rates and credits shift each year, so check the current brackets before filing to estimate your state tax liability. For example, a single filer with $70,000 earned in a given year would fall into a different bracket than a couple filing jointly with the same income.
Tradeoffs to consider:
- Connecticut may offer credits such as earned income tax credits that interact with federal ones, potentially altering your tax refund or tax due. If you earned $40,000 as a qualifying worker, you might see a state credit that reduces your bill by several hundred dollars.
- Local and school taxes can raise your overall tax burden even when the state rate is modest. For example, a city with a 1.5% local levy adds up on a $60,000 income.
| Topic: Understanding the implications of taxes in 2026. | What to know about filing an amended return for previous tax years. | Action |
|---|---|---|
| State income tax | Rates by filing status; annual updates | Review brackets, claim credits |
| Filing | State return paired with federal return | Gather tax documents and file form to ensure accurate reporting. |
| Credits | Possible state credits that affect refunds | Check eligibility early |
County & city taxes
County and city taxes can add extra charges on top of state and federal duties. They often show up as property taxes, local sales taxes, or special assessments, and they vary by place, affecting your overall tax due. 🧭
What to watch for:
- Local rates: Some counties or cities set their own rates on top of state taxes, especially for services like local roads, schools, or parks. For example, a city may add a 0.5% local sales tax you see only at checkout.
- Property tax impact: If you own a home, your county or city may bill annual property taxes that affect your monthly budget, especially in relation to taxes in 2026. A $300,000 home could incur roughly $3,000 or $6,000 per year depending on the rate and exemptions, impacting your tax situation.
- Local credits or exemptions: Some areas offer credits or exemptions for seniors, veterans, or low-income residents. A senior exemption might shave several hundred dollars off your bill.
Practical steps you can take:
- Check your local assessor or treasurer website for current rates, due dates, and any equalization factors that change your bill year to year.
- Estimate your annual local tax using last year’s bill and expected changes in assessed value. If your home’s value rose 5% but the rate stayed the same, recalculate accordingly.
- Coordinate with your state filing to avoid surprises in the tax bill or refunds, especially regarding tax dates. If you expect a refund, verify whether local taxes are part of the withholding adjustments.
Earned income tax tips
Earned income tax tips help you maximize credits and minimize mistakes on your federal and state returns. Start by identifying which credits you qualify for and gathering the right documents to prove your income. 🧾
Practical steps you can take now
- Before you file, confirm eligibility for the earned income tax credit and child tax credit to avoid missing out or delaying refunds. 🤔
- Gather W-2s, 1099s, and any self-employment records in one place. Use a simple checklist and cross off items as you collect them.
- Do a quick refund estimate using last year as a baseline, then adjust for any income or withholding changes. 💡
Filing taxes: tips & locations
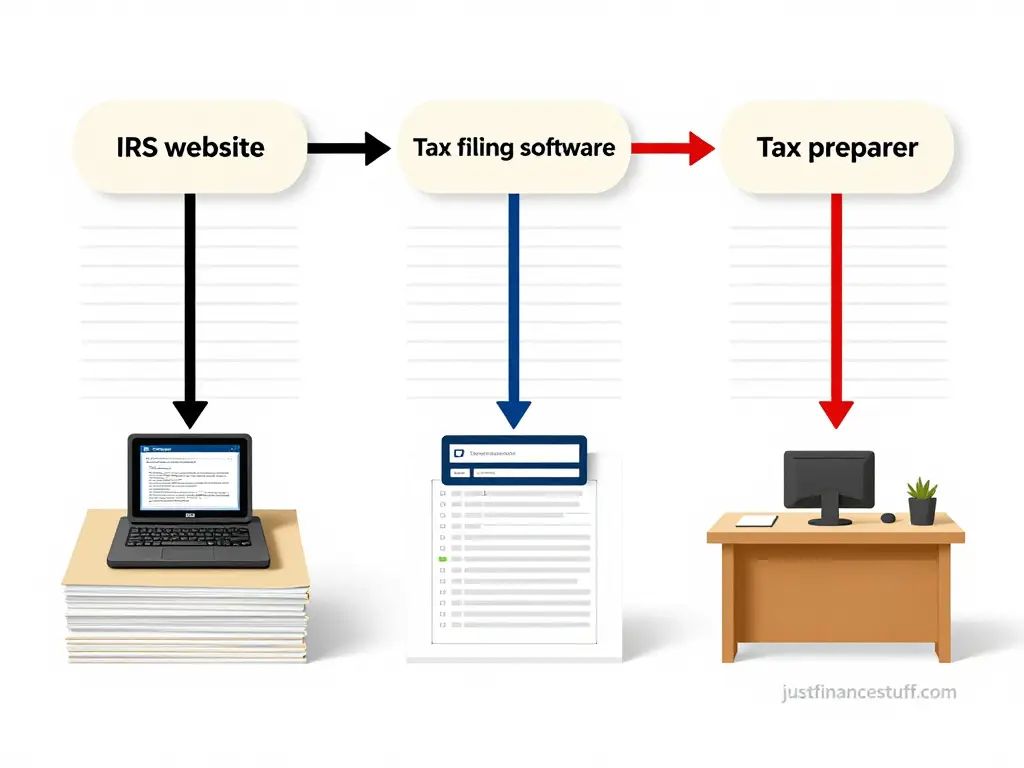
Filing taxes efficiently saves time and reduces errors. The key steps are gathering documents, choosing how to file, and knowing where to submit. This section gives practical tips and where to file in person or online. 🗂️
Start with these quick tips:
- Organize documents by form type: W-2s, 1099s, mortgage interest, and charitable receipts.
- Decide your filing method: electronic filing tends to be faster and can include direct payments or refunds.
- Check deadlines: missing a date can trigger a penalty for filing or balance due alerts.
- Use prior year data as a guide for estimate calculations and credit eligibility like the Earned Income Tax Credit or Child Tax Credit.
| Location | Pros | Notes |
|---|---|---|
| IRS website | Free or low-cost filing, instant refund status updates | Best for federal and most state returns in the 2025 tax year. |
| Tax filing software | Step-by-step guidance, audit risk checks | May charge for premium features |
| Tax preparer | Personalized help for complex situations | Expect a fee, share all income details |
If you want savings, compare free filing options and verify eligibility before you start. Remember to keep copies of your tax documents and confirmation numbers until the process is complete. 🧾
Free tax filing resources
Finding free options to file your federal and state returns can save you money, especially if your income is modest. Here are reliable paths to consider and what to expect from each. 🧾
- IRS Free File: A straightforward path for eligible filers to file federal returns online at no cost, with partner software options that guide you through the process. A common scenario is a single filer with W-2 income under $73,000 who can file federal and state returns for free.
- Volunteer Income Tax Assistance (VITA): In-person or virtual help from trained volunteers for qualifying taxpayers, typically with simpler returns and basic credits. If you qualify, bring your last pay stub, Social Security card, and proof of deductible expenses to speed things up.
- Tax preparation software free tiers: Some providers offer no-cost versions for simple returns, especially useful during the filing season. Check eligibility by income, filing status, or required forms; a basic 1040 with a standard deduction and one W-2 is common, but schedules or itemized deductions may require paid tiers.
| Option | Who qualifies | What you get |
|---|---|---|
| IRS Free File | Most filers with simple returns; income limits may apply for the 2025 tax year. | Federal return filing at no charge; some states included |
| VITA / Tax Clinics can assist you with filing your return and understanding your tax situation. | Low to moderate income, seniors, people with disabilities | In-person help, basic forms, guidance on credits |
| Free software tiers can help you file form for your individual taxes efficiently. | Filers with straightforward income and standard deduction | Guided prompts, e filing; additions may cost |
Before you start, gather your W-2s, 1099s, and any notices from the IRS or state tax agencies related to your individual income tax. Compare options for the specific forms you need and watch for hidden fees in the fine print. 💡
Future tax bracket trends
Tax brackets can shift with economic growth and policy changes. Here’s what to watch for in the near and mid term to plan ahead. 📈 Knowing how changes show up in real life helps you adjust withholding, estimated payments, and retirement contributions now.
- Watch for updates after new laws or budget proposals. Brackets can move to reflect inflation, wage growth, or policy goals. For example, a mid-year proposal might raise the top of the 22% bracket to avoid bracket creep, changing your liability if you earn just over that threshold.
- Brackets may adjust annually for inflation. This helps protect your take home pay from bracket creep without extra action. Expect modest bumps: $100, $300 more usable income for many households if you notice the standard deduction staying aligned with price increases.
- High earners could see targeted changes. Expect narrow changes that aim to fund programs, not broad tax overhauls. A small rise in upper-bracket rates or an added Medicare surtax could affect households near the top, while most filers see little to no change.
Understanding potential shifts helps with planning your withholdings, estimated tax payments, and retirement contributions. Here’s a quick look at how a bracket change could affect a hypothetical household. 🧮
Always verify the posted tax year brackets when you prepare. Compare expected changes to your current withholdings and adjust if needed. ⚖️
Local tax payment options
Local tax payments let you settle city or county charges directly. Here are practical options to avoid late fees and keep records tidy. 💳 This guide shows real actions you can take right now to stay on top of bills and capture proof of payment.
- Online portals: Many cities offer secure portals for direct credit card or bank transfer. After paying, save or email the confirmation number and download the receipt for your records.
- Mail in payments: Send a check or money order with the bill’s coupon and keep a postal receipt. For large balances due, consider sending a traceable mail option to prove the date of mailing for your federal tax return.
- In person: Visit designated payment centers during business hours to pay with cash, card, or check. Ask for a stamped receipt and note the clerk’s name and time of payment.
Before paying, verify the exact amount due, including any penalties or interest from prior periods. If your local tax bill shows a balance due, you may have options to set up a payment plan, such as splitting the balance into monthly installments over 6 or 12 months to pay the tax. 🧾
| Payment method | Pros | Things to watch |
|---|---|---|
| Online portal | Fast, receipts emailed, easy tracking | Fees or processing limits may apply; ensure you’re on the official site for filing your federal tax return. |
| No tech needed, good for records, but consider using tax pro services for more complex individual income tax returns. | Postal delays can affect timing; use trackable mail if possible to ensure your documents arrive during the filing season. | |
| In person | Immediate confirmation, cash options sometimes | Travel time and hours matter; bring ID and bill copy |
| Automatic withdrawals | Reduces late filings, predictable timing | Requires setup and bank info; monitor for failed drafts |
If you miss a deadline, contact the local tax office early to discuss extensions or payoff plans. Keeping copies of all payment confirmations helps resolve any later disputes. 🗂️
Paycheck tax deductions
Understanding paycheck tax deductions helps you see what comes out of every paycheck and why. It also shows how changes to withholding affect your refund or balance due at tax time. 🧾
Most workers see two main categories: mandatory withholdings and optional deductions, which can affect their credit or refund. Mandatory withholdings fund federal and state programs, while optional items can reduce take-home pay but may offer future benefits when you file your tax return for tax year 2024. 💡
Common deductions to expect
- Federal income tax withholding based on your W-4 selections
- Social Security and Medicare (FICA) taxes
- State income tax withholding where applicable
- Pre tax contributions can affect your individual income tax situation. to retirement plans or health savings accounts
- Insurance premiums Paid through payroll (if your employer offers them) can help with your federal tax return and potentially lead to a credit or refund.
How to optimize your withholding
- Check your take-home pay after changes to avoid surprises at year end.
- Do a quick projection: if you expect a raise, use a paycheck calculator to see how it shifts your net pay and potential refund.
- Schedule a mid-year W-4 review after life events like marriage, kids, or a new job to keep withholding aligned with your situation.
Track any pre tax contributions and keep records of changes. This helps you maximize deductions when you file the federal income tax return and state returns. 🧾
Selling property tax insights
Selling property can trigger several tax events that affect your federal and state taxes. Here’s a practical look at what to expect and how to plan ahead. 🏡💡
- Capital gains: If you sell for more than you paid, you may owe capital gains tax on the profit. The rate depends on how long you owned the property and your overall income. For example, a property sold after 1 year might face short term rates, while a 2+ year hold could qualify for lower long term rates.
- Primary residence exclusion: If the home was your main residence for at least two of the last five years, you might exclude a portion of the gain from federal taxes. In practice, you might exclude up to $250,000 single or $500,000 married filing jointly, subject to eligibility.
- Basis adjustments: Improvements you made while you owned the property can increase your basis, lowering taxable gain when you sell. Think kitchen remodels, adding a bathroom, or finishing a basement with receipts and dates for your individual income tax returns.
- State taxes: Many states tax gains differently from federal rules, so check your state tax return for any specific exclusions or rates. Some states mirror federal breaks, others do not.
Before listing, gather tax documents related to the property, including basis, improvements, and any prior deductions. This helps reduce surprises at filing time. 🧾
Social security & taxes
Social security and taxes intersect in several practical ways that affect your take home pay and retirement planning. Understanding these links helps you predict how benefits and taxes will look after you stop working during the 2025-2026 tax filing season. 🧓💵
Here are the main points to know:
- Social Security benefits may be taxable depending on your total income and filing status.
- Tax forms like the 1040 and Schedule B may include lines for reporting Social Security benefits.
- State rules for taxing Social Security differ, so your state return might tax benefits differently from federal rules.
How benefits may become taxable
- If your combined income exceeds specific thresholds, a portion of benefits can be taxed at the federal level.
- Thresholds consider your adjusted gross income, nontaxable interest, and half of your Social Security benefits.
- Example: a couple filing jointly with a combined income around $55,000 in retirement might see up to 50% of benefits taxed, depending on other deductions.
Keep copies of Social Security statements and tax forms to verify what was reported. This helps prevent errors and speeds up filing. 🗂️
State tax refunds guide
State tax refunds depend on your state rules, filing status, and how much you overpaid during the year. A practical plan is to check your state refund status early and track processing times so you know when to expect your money. 🧭
Key steps To maximize clarity and speed during the filing season, consider consulting a tax pro.
- Gather tax documents early, including W-2s and 1099s, to ensure accuracy on your state return. 🗂️
- Choose the right deductions to optimize your federal tax return for tax year 2024. tax form for your situation to avoid errors that slow refunds. 🧾
- File electronically to receive faster processing and safer delivery of the tax return for tax year 2024. state refund. 💨
Common factors that influence refunds:
- State withholding and estimated payments can shrink or grow your refund. 💰
- Credits specific to your state, like child or earned income credits, can boost refunds when you qualify for tax year 2024. 👶
- Any mistakes or mismatched information can delay refunds until you correct them. ⚠️
Real‑world tips to speed refunds:
- Use the state tracker after filing to see where your return is in the queue and your expected payment date. ⏱️
- Double‑check your name, SSN or ITIN, and address exactly as they appear on your documents to avoid processing holds. 🧭
- If you owe other debts, understand how they might offset your refund and plan a separate payment to avoid surprises. 💳
Tax deadlines & filing status
Know the key dates and your filing status to avoid penalties and delays. The main deadline for federal taxes is April 15, but it can shift if it lands on a weekend or holiday. Always check the IRS calendar for the exact date each year. 🗓️
Your filing status affects your tax rates, standard deduction, and eligibility for credits. Common options include single, married filing jointly, married filing separately, head of household, and qualifying widow(er). Pick the one that matches your situation to minimize your tax bill. 🧭
Quick checks before you file
- Confirm your correct filing status based on your household in the previous year. For example, if you separated last year but aren’t officially divorced, you might still file jointly or as head of household depending on dependents.
- Verify your personal information on the tax form to avoid processing delays. Double check names, Social Security numbers, and addresses for everyone on the return.
- Decide if you will itemize deductions or take the standard deduction, depending on which lowers your tax liability more. If you bought a home or paid significant medical expenses, itemizing could save you hundreds to thousands.
| Aspect | Impact of taxes paid on your overall financial health. | Tip |
|---|---|---|
| Deadline | Missed dates can trigger penalties, making it essential to stay informed about tax dates. | Mark the IRS date for your federal tax return on your calendar and set a 1-week pre-deadline reminder. |
| Filing status | Affects rates and credits | Choose the one that reflects your situation best, review after life changes |
| Extensions | Gives more time to file your 2025 tax return. | Do not delay tax payments due; even with an extension, estimate and pay what you owe for taxes in 2026. |
U.s. state tax questions
State taxes vary widely by state, and your final bill depends on where you live, your income, and how you file. The core idea is to check your state’s withholding rules, credits, and refunds for the current tax year. 🧭 For example, a commuter who works in one state but lives in another may see different withholding rules and credit opportunities that cut or raise the amount due at filing.
Practical notes for common scenarios
Common questions include how to handle state filings when you move mid year, whether state credits line up with federal credits, and how estimated payments influence your state liability. Here are actionable steps to stay on track:
- Compare state credits carefully versus federal credits. For instance, a state may offer a child credit that phases out sooner than the federal version, reducing your overall benefit. 🎯
- File even when you don’t owe in some states to claim refunds or specific credits. If you miss the deadline, you might lose eligible money. 🧾
- Match withholding to your actual income by reviewing your last pay stub. If you moved or received a bonus, adjust W-4 state withholding to avoid a big spring surprise. 💼
If you’re filing across multiple states, track income by state and use the correct forms to prevent delays or mismatched credits. Keep copies of W-2s and 1099s by state so you can verify where each payment belongs. 🗂️
Understanding tax accounts
Tax accounts help you track what you owe, what you’ve paid, and what you might get back. They keep everything organized across federal, state, and local taxes, which is crucial for filing an amended return. Knowing how these accounts work makes filing easier and cuts surprises at payment time. 💡
There are three main kinds of tax accounts to know:
- Federal tax accountTracks your federal income tax, credits like the earned income tax credit, and any refunds or balance due with the IRS during the filing season. It updates when you file, pay, or adjust with amendments. For example, if you claim a new credit this year, your federal account will shift balances accordingly within days after you file.
- State tax account: mirrors your state filing, refunds, and any balance due. It can differ in rules from federal, so review state guidance carefully. If your state offers a child tax credit or renter credit, expect separate entries and deadlines from the federal ones.
- Estimated tax accounts: used when you owe taxes throughout the year rather than in one lump sum. You make periodic payments to avoid a large balance at year end. A practical approach is to schedule quarterly reminders and set payments of about 25% of your expected annual bill, then adjust after spring or fall withholding changes.
Conclusion
Taxes stay complex but manageable when you stay organized and proactive, especially with the help of tax professionals. A simple, steady plan helps you dodge surprises and keeps refunds or balances predictable. 🧭
If your situation changes, revisit your filing status and potential credits like the earned income tax credit or child tax credit to maximize benefits. 🧒💬
FAQs
Here are quick, practical answers to common questions about filing, refunds, and deductions. If you see your question here, you’ll know the basics fast. 💡
- What is a tax return and why do I file it? A tax return reports your income, deductions, and credits to calculate your tax liability and determine if you owe money or get a refund. 🧾 For example, if you earned $50,000 and claimed $8,000 in deductions, your tax would be based on $42,000 of taxable income.
- What is a tax refund and when do I get it? A tax refund is money returned if you overpaid through withholding or credits. Refunds typically arrive after filing, depending on method and processing times. 💳 If you overwithheld $2,000 over the year and qualify for a $1,500 credit, you might see a refund sooner when you file electronically with direct deposit.