Why money management matters
Money management helps protect your finances and plan for the future. Good habits today harden your money management skills. financial security and set up a solid financial foundation for tomorrow, whether you face a job loss, a medical cost, or a big purchase like a car or home. With clear budgeting, you can implement tips to improve your finances. save money, reduce debt costs, and keep your spending in check. This guide focuses on practical steps you can take now to improve your personal finances and feel more in control of your money journey.
What you will learn
You will learn how to:
- Create a realistic budget that matches your monthly income and monthly expenses.
- Build and maintain an emergency fund to cover unexpected costs such as car repair or medical bills.
- Handle your credit card debt effectively to avoid higher interest rates. debt strategically and choose the right repayment path.
- Automate your finances to stay on track with savings and bill payments.
- Track spending and cut unnecessary costs to free up money for goals like retirement contributions and savings growth.
- Set and pursue both financial goals and good spending habits. short-term goals and long-term ambitions, improving your financial literacy.
Create a Realistic Budget
Creating a realistic budget starts with knowing exactly what comes in each month and where it goes. A solid budget helps you align your spending with your goals, from building an emergency fund to saving for a retirement account. This section covers practical steps to map your money and keep it under control.
Tracking income and expenses
Start by listing monthly income, including your salary and any side gigs. Then track every expense for a month to see the true flow of money. This reveals where you can adjust and where you might be overspending.
- Income: monthly income from all sources, after taxes.
- Expenses: monthly costs like housing, food, transport, and debt payments.
Allocating for essential and discretionary spending
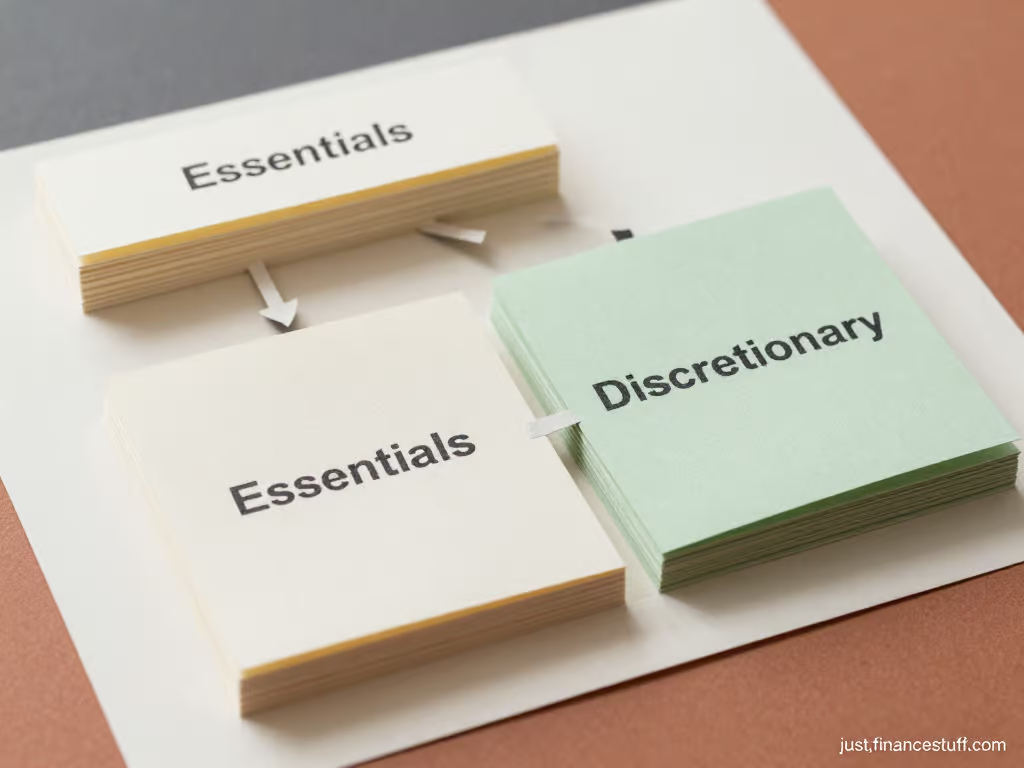
Divide what you have into two main buckets. Essentials cover needs you must pay for each month, while discretionary items are flexible. This split makes it easier to protect basics while still enjoying life.
| Category | Example | Guideline |
|---|---|---|
| Essentials | Rent or mortgage, utilities, groceries | Cover first, then allocate remaining to other areas |
| Discretionary | Dining out, entertainment, new gadgets | Limit to a fixed cap to protect essentials |
Tip: use a simple tool or app to categorize every expense as you go. This speeds up follow-up adjustments and keeps you on track with your budget and savings goals.
Next, you’ll learn how to build an emergency fund and keep it growing as part of a complete money management plan.
Build and Maintain an emergency fund
A dedicated emergency fund protects you from sudden costs and keeps your financial plan on track. A clear goal and a safe place to store it are the first steps to financial security. emergency fund is a safety net you can rely on when life throws a curveball.
How much to save
Start with a goal of three to six months of essential expenses. If you have a stable job and predictable costs, aim for three months. If your income is variable or you have dependents, target six months. Break it down into a monthly target you can reach in small steps to achieve your financial goals.
Where to keep emergency funds
Choose a liquid, accessible account so you can withdraw quickly when needed for your budget. A savings account or a high‑yield option at a credit union or bank keeps your money safe while still earning some interest. Avoid tying it up in investments that could lose value in the short term.
When to use it
Dip into this fund only for true emergencies such as job loss, urgent car repairs, or medical costs not covered by insurance. If you use it for non‑essential purchases, rebuild it as soon as possible to preserve financial security.
| Aspect | Guidance |
|---|---|
| Target amount | Three to six months of essential expenses is a crucial part of financial education. |
| Location can impact your financial decisions and available credit options. | Savings account or high‑yield option at a credit union or bank |
| Use case | Job loss, urgent repairs, unexpected medical bills |
Progress tip: automate small monthly deposits until you hit your goal, then maintain the fund with regular top‑ups after any withdrawal.
Tackle debt strategically
Debt costs money and limits your options. A smart plan lowers interest and keeps you in control of your financial future. This section helps you decide where to focus, compare repayment methods, and stay on track with minimum payments.
Prioritizing high-interest debt
Start by listing all debts and their interest rates. Pay extra toward the highest rate while making minimum payments on the rest. This approach typically reduces the total interest rates you pay over time and helps you clear risky balances sooner.
- Identify debts with the highest annual percentage rate (APR).
- Target these first while keeping minimums on others.
- Reassess monthly to adjust if rates change or balances move.
Snowball vs avalanche methods
Two common paths exist. Snowball pays the smallest balance first to gain momentum, while avalanche targets the biggest interest burden first for lower total cost. Choose based on what keeps you motivated and fits your situation to improve your spending habits.
- Snowball: quick wins, builds confidence.
- Avalanche: saves money long term by cutting high costs first.
Keeping minimum payments on track
Always pay at least the minimum on every debt to avoid penalties and a hit to your credit score. Set up automatic reminders or transfers to ensure on‑time payments even when life gets busy.
Automate your finances
Automating money tasks saves time and reduces mistakes in your personal finance management. Set up systems that handle bills and savings without you thinking about it, so you stay on top of your financial plan and avoid late fees.
Automatic bill payments
Link your checking account to essential services and set up recurring payments for rent, utilities, and loan obligations. This helps keep your finances stable and protects your credit by avoiding missed payments.
- Choose a single date each month to align with your paycheck.
- Review due amounts before each payment cycle to catch changes.
- Keep a small buffer in your checking account for timing delays.
Scheduled transfers to savings
Automatically move a portion of your monthly income to a savings or retirement account. This builds your emergency fund and supports long term goals like retirement and big purchases.
- Set a realistic transfer amount that fits your budget and expenses.
- Increase the transfer after raises or when discretionary spending drops.
- Ensure transfers occur after bills are paid to preserve cash flow.
Rewarding consistency
Track progress with simple indicators and celebrate steady discipline. Small, predictable steps compound over time to improve your financial security and reduce stress.
| Automation tip | Benefit |
|---|---|
| Bill payments on time | Maintains financial stability and protects credit health |
| Regular savings transfers | Gradual, reliable growth of emergency funds and goals is essential for overall financial well-being. |
| Review cadence | Keeps your plan aligned with life changes |
Track spending and cut unnecessary costs
Tracking where your money goes helps you find obvious places to save. Start simple, then refine your budget as you learn what moves your finances forward.
Using simple tracking tools
Record income and expenses for a month using a basic notebook or a free app that categorizes spending. The goal is to spot patterns, not chase perfection.
- Record every purchase, even small ones like coffee or snacks.
- Group spending into essentials and discretionary items to spot quick wins.
- Review at the start of each week to adjust allocations for the month.
Identifying recurring charges to renegotiate or cancel
Recurring payments can quietly drain cash. Look for subscriptions, memberships, or services you rarely use and decide what to renegotiate or drop.
- List all subscriptions and their monthly cost.
- Check for free alternatives or cheaper plans.
- Call providers to negotiate lower rates or switch to annual billing if it saves money.
| Recurring charges can affect your financial well-being if not monitored. | Action | Potential monthly saving |
|---|---|---|
| Streaming service | Downgrade plan or cancel | $5-$15 can be a good starting point for your emergency fund. |
| Gym membership | Pause or cancel | $10-$50 |
| Software trial | Uninstall or switch to free tier | $0-$20 |
Save for goals: short-term and long-term
Clear goal setting
Name concrete goals that matter to you. A short-term goal could be setting aside a monthly amount for an emergency fund, while a long-term goal might be saving for retirement or a down payment. Clear goals keep you focused and help you track progress over time.
Allocation by priority and timeline
Split your savings by priority and when you want it reached. For example, allocate 60% to an emergency fund until you hit three to six months of expenses, 25% toward a retirement account, and 15% for a specific big purchase. Adjust as your income or expenses change.
- Emergency fund: three to six months of essential expenses.
- Retirement savings: contribute to a retirement account such as an RRSP or TFSA as soon as possible.
- Big purchases: set a timeline and build a dedicated savings target.
Reviewing progress
Check progress monthly to stay on track. Compare actual savings to your plan, adjust contributions if you receive a raise or reduce discretionary spending, and reset goals if life changes demand a new plan.
| Goal type | Recommended timeline | Suggested allocation |
|---|---|---|
| Emergency fund | 3-6 months of expenses | 40-60% |
| Retirement savings | Long-term | 20-40% |
| Big purchase | 6-24 months | 10-20% |
Protect your finances
Insurance basics
Having the right coverage shields you from unexpected costs that could derail your financial plan. Start with essential protections like life and health plans, then consider home and auto policies based on your needs and risks.
- Review your policy terms to know what is covered and what isn’t for better financial education.
- Choose deductibles that fit your monthly budget to balance premiums and out-of-pocket costs.
- Update beneficiaries after major life events to ensure your money goes where you intend in your financial plan.
Safeguards to prevent debt spirals
Smart safeguards stop debt from growing when emergencies hit. Build buffers and use tools that curb small, repeated charges or high-interest balances before they get out of hand.
- Keep a debt clearance plan that targets high-interest balances first.
- Set up alerts for due dates to avoid late fees and penalty interest.
- Use lower-cost credit options when possible, and avoid piling new debt during tough months.
Identity theft prevention
Protecting personal data reduces fraud risk that takes time and money to fix. Build simple, repeatable safeguards you can stick with.
- Use unique, strong passwords and two-factor authentication for important accounts.
- Monitor your credit reports regularly to catch unauthorized activity early as part of your personal finance strategy.
- Shred sensitive documents and limit sharing of personal information online and offline.
FAQ
Here are quick answers to common questions about money management and building solid financial health.
- What is money management? It means making informed decisions about how you earn, spend, save, and borrow to reach your financial goals.
- How much should I keep in an emergency fund? A common goal is three to six months of essential expenses, but adjust to your job stability and family needs for better financial decisions.
- What is a good way to start budgeting? List all monthly income and expenses, then categorize for essentials and discretionary spending to see where you can save.
- Should I pay off debt or save at the same time? It depends on interest costs. Prioritize high-interest debt while saving a small emergency fund to reduce risk.
- How can I improve my credit score to achieve my financial goals? Pay bills on time, keep credit usage low, and review your credit report for errors at least once a year.
- What is the difference between a checking account and a savings account? A checking account handles daily spending and bills; a savings account stores money for future goals and earns interest.
- Is automation safe for my money management skills? Yes, when you set up automatic payments and transfers carefully, you reduce late fees and stay consistent with savings.
- What should I do if my financial situation changes? Revisit your budget, adjust savings goals, and tighten discretionary spending until stability returns.
If you want a simple, practical plan, start by defining a monthly financial goal, then build a budget that channels money toward an emergency fund, debt reduction, and a savings account for short-term needs.
Conclusion
Managing your money is an ongoing, practical process. A clear financial plan guides you from today toward financial security tomorrow, with steps you can start now.
Here are the essentials to keep you on track:
- Create a budget that lays out monthly income and expenses, separating essentials from discretionary spending to enhance your financial literacy and well-being.
- Build an emergency fund covering three to six months of expenses in your emergency fund is a key financial goal. income and expenses to weather job changes or unexpected costs.
- Pay down high‑cost debt first and automate savings to keep momentum without extra effort.
- Protect your finances with basic life insurance, appropriate home or auto coverage, and incorporating fraud prevention habits into your personal finance routine.
- Track progress regularly and adjust your financial goals as circumstances change, like a salary increase or a major purchase.
Start simple: set a savings goal and a short‑term plan to reach it, then expand toward longer aims like retirement accounts and TFSA or other equivalent options.
Next step: review your current Understanding your financial situation is crucial for effective money management. and choose one action to implement this month that moves you closer to financial stability and a healthier money management routine.