Connecticut tax overview
This Connecticut tax overview explains how state finances fund services and how taxes affect personal and business money decisions. It highlights the main tax types, income tax, sales tax, property tax, and business taxes, and how 2026 changes could shift the burden for households and companies.
The section also points to key ideas you will see later, such as the progressive income tax with multiple brackets, the base sales tax rate, and how local governments influence property bills. The goal is to help you estimate your total tax load and identify where you may optimize deductions, credits, or planning moves within the law.
If you want a quick sense of the lay of the land, here are the core components to watch in 2026:
- Income tax structure and brackets that affect take-home pay.
- Sales tax on goods and many services, with common exceptions.
- Property tax context and how local rates shape bills.
- Business taxes including corporate and pass-through considerations.
Income tax rates and brackets
The Connecticut state income tax uses a progressive system with seven brackets that apply to portions of income. Higher income is taxed at higher rates, while lower income portions are taxed at lower rates. Deductions and credits can shift how much income falls into each bracket.
Overview of the seven brackets
Each bracket covers a specific range of taxable income, with the portion inside that range taxed at its corresponding rate in the context of Connecticut’s personal income tax. Deductions and credits reduce the amount of income that is taxed in each bracket, which can affect overall liability.
- Bracket 1: the lowest rate applies to the first portion of income
- Bracket 2: a slightly higher rate for the next slice
- Bracket 3: mid-range income taxed at an intermediate rate
- Bracket 4: middle-high incomes face a higher rate
- Bracket 5: further income bands taxed at another ascent
- Bracket 6: near-top earnings taxed at a high rate under the Connecticut state tax system.
- Bracket 7: the top marginal rate applies to the highest income slice
The top marginal rate is 6.99 percent. This rate applies only to the portion of income that exceeds the bracket threshold; lower portions are taxed at their respective rates.
Top marginal rate and how it affects earners
The 6.99 percent top rate matters most to higher earners. It does not apply to all income, only to the portion that crosses the top bracket’s threshold. Even small income increases can push more earnings into the higher bracket, increasing the tax on the last dollars earned.
Key points to understand:
- The rate is applied progressively; not all income faces 6.99 percent.
- Bracket thresholds determine how much income sits in each rate level.
- Deductions and credits reduce taxable income, which can keep portions of income in lower brackets under the Connecticut state tax system.
Sales tax and taxable goods
The base sales tax rate in Connecticut is 6.35 percent. This rate applies to most goods and some services sold within the state and is the default shoppers should expect at checkout.
Base rate and common exceptions
Most purchases fall under the 6.35 percent base rate, but some items use different rules or rates. Knowing these helps prevent surprises at checkout.
- Meals, prepared foods, and certain services may carry different rates or exemptions.
- Localities in Connecticut do not add separate sales tax layers, so 6.35 percent is the statewide rate for standard transactions.
- Certain items may be exempt from sales tax, such as essential goods or some medical items, depending on current law.
What items are taxed at different rates
Beyond the base rate, a small subset of items is taxed differently or exempt, affecting the total tax on a purchase that includes these items.
| Item or category | Tax treatment |
|---|---|
| Meals and prepared foods | Often taxed at the base rate, with possible exceptions |
| Gas and motor fuels | Subject to the state gas tax structure in addition to sales tax |
| Medicines and certain medical devices | Typically exempt or differently regulated |
Keep in mind that the overall tax burden includes both the base rate and any related exemptions or surcharges. The exact tax due depends on the item mix and how tax credits or exemptions are applied in specific transactions under Connecticut state tax regulations.
Property tax context and homeowners’ burden
Connecticut homeowners pay property taxes set by state rules but collected by towns and cities based on local values and levies. The state provides the framework; actual bills come from local assessments and mill rates. This can make neighboring homes with similar values have different tax bills.
Effective property tax rate and impact
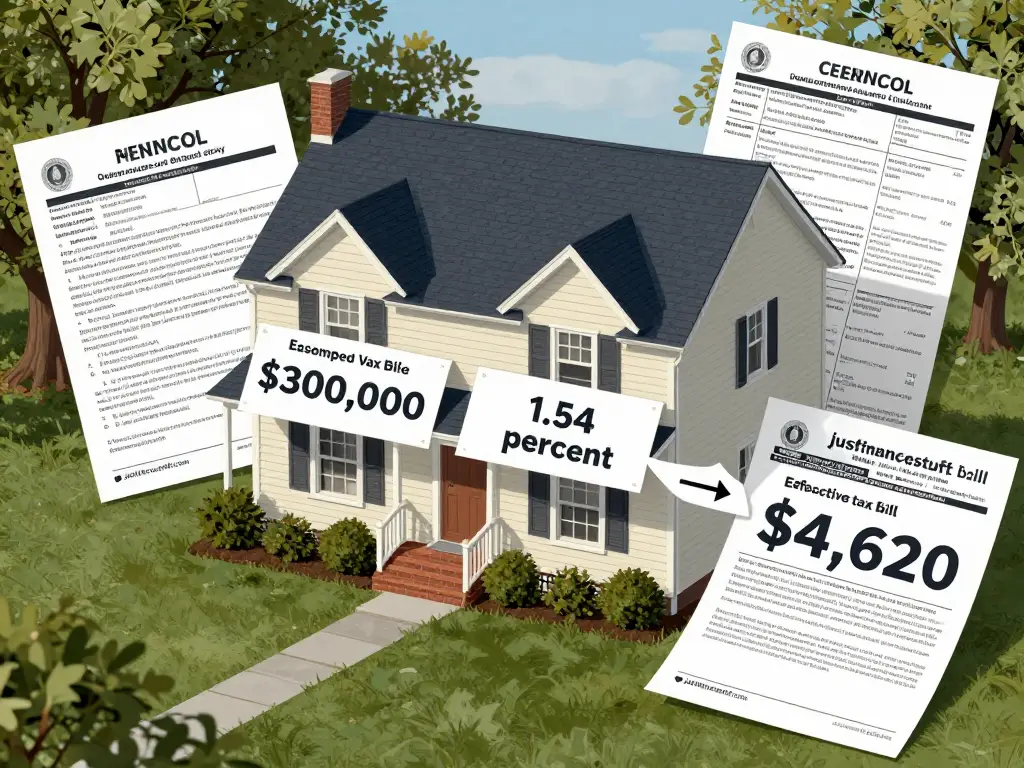
Average effective rate is about 1.54 percent for owner-occupied homes. The rate uses assessed value and local mill rates to calculate yearly taxes. A $300,000 home could owe roughly $4,620 annually at that rate, before exemptions or credits.
- Higher home values raise the dollar tax even if the rate stays the same.
- Exemptions and credits reduce bills for eligible homeowners, such as seniors or disabled residents in some towns.
- Local budget changes can shift the burden from year to year.
How local variation affects payments
Local differences matter in practice. Towns set their own mill rates, which multiply the assessed value to determine taxes. Small changes in value or rate can change yearly payments.
| Factor | How it affects your bill |
|---|---|
| Assessed value | Higher value increases taxes at the same rate |
| Municipal mill rate | Different towns charge more or less per dollar of value |
| Exemptions and credits | Reduce the bill for qualified homeowners |
Corporate and business taxes
Corporation Business Tax basics and top rate
The Connecticut Corporation Business Tax applies to most business income earned in the state. The base and top rate structure targets larger profits, shaping the overall tax burden for sizable corporate income under the Connecticut tax system.
- Taxable base typically includes Connecticut net income and apportionment adjustments.
- Some sectors may face additional surcharges or brackets based on income and industry rules.
- Filing requirements follow state corporate income tax rules, including estimated payments for revenue thresholds.
Pass-through entity tax considerations
Connecticut also taxes pass-through entities, where income passes to owners and is taxed at individual rates. The pass-through tax is optional for some entities and includes a credit to mitigate double taxation at the owner level.
- When elected, the entity pays a rate reflecting the business’s Connecticut presence, with owners reporting the credit on their personal returns.
- The choice to participate depends on how owners itemize deductions and credits at the individual level.
- Considerations include how losses, distributions, and allocations affect the total tax burden for both the entity and its members.
Estate, gift, and retirement considerations
Estate and gift tax landscape
Connecticut operates its own estate and gift tax framework, separate from the federal rules. Transfers at death and large gifts can influence your planning even if federal exemptions would cover similar amounts.
Key considerations include state thresholds, lifetime gifting, and how exemptions interact with state calculations. Because state rules can diverge from federal rules, map how a Connecticut plan translates into the total tax picture.
- State-level transfer taxes may apply to sizable estates or gifts above thresholds.
- Gifting moves can influence both Connecticut and federal tax outcomes.
Retirement income treatment and exemptions
Connecticut taxes retirement income differently from other income categories, and some retirement earnings may be exempt or partially exempt for eligible filers.
The rules hinge on how retirement income is counted for state purposes and where the thresholds apply as income rises, which can affect net take-home totals in the Connecticut tax system.
- Public pensions and certain retirement benefits may qualify for targeted exemptions.
- Phaseouts can reduce exemptions for higher federal adjusted gross incomes.
2026 legislative changes and impacts
Key developments from the 2026 session
The 2026 session updated several tax rules to align with state priorities, including income tax, corporate tax, and administration. The changes focus on simplification and targeted relief, with selective conformity to federal rules to reduce distortions for Connecticut filers.
- Adjustments to corporate and pass-through entity tax treatment to improve competitiveness.
- Modifications to exemptions and credits that affect personal and business liabilities.
- Clarifications in filing deadlines and reporting requirements to streamline administration.
Expected effects on households and businesses
Household tax burden may shift modestly, depending on income and family structure. Retirees and high-deduction filers could notice the impact of new exemptions and tax credits in the Connecticut state tax landscape.
- Households with business income flowing to owners may see changes via pass-through credits.
- Businesses might face altered marginal rates or brackets at certain revenue levels.
- Filing processes could become more straightforward, reducing compliance time for many filers.
Planning and tax calculator tools
Planning your Connecticut tax picture starts with a clear view of your personal income tax situation. You should aim for a realistic estimate of your total tax burden, including income, sales, and property taxes where they apply. Start with a simple snapshot of earnings, filing status, and major deductions to ground your planning.
Tips for estimating personal tax liability
Use practical steps to sharpen your estimate of Connecticut state tax without overcomplicating things:
- Identify your filing status and the number of dependents to determine your standard deduction and credits.
- Separate federal and state considerations. Connecticut uses its own brackets and rules that differ from federal calculations.
- Estimate taxable income by subtracting deductions and exemptions from gross income.
- Account for the progressive rate structure. A small rise in income can push a portion into a higher bracket, affecting only the income in that bracket.
- Include special items such as pass-through entity effects if they apply to you.
How to use calculators effectively (without links)
Calculators help when used with clear inputs and a sanity check:
- Enter current wages, 2026 adjustments, and any retirement or investment income separately to see where each portion falls.
- Input expected deductions and credits you expect to claim on your state return. If uncertain, use a cautious range to bracket possible outcomes.
- Compare scenarios: different filing statuses, income changes, or changes in deductions to gauge sensitivity.
- Check consistency with known limits, such as bracket thresholds and credit caps, to avoid overestimation.
FAQ
Here are concise answers to common questions about Connecticut taxes for 2026, based on the current rules and context of the state tax system.
- What are the Connecticut income tax rates in 2026? Connecticut uses a progressive income tax with multiple brackets. The rates range from 2 percent up to the top marginal rate of 6.99 percent, applying to different portions of taxable income depending on filing status in the Connecticut state tax system.
- Is the sales tax the same for all goods? The base state sales tax is 6.35 percent on most goods and some services. Certain items may be taxed at different rates or exempt from tax, depending on category and use.
- How does property tax work in Connecticut? Property tax is levied at the local level rather than by the state. The state provides context on an average effective rate, but actual bills depend on assessed value and local mill rates.
- What about corporate and pass-through taxes? The state has a corporate income tax and a pass-through entity tax option. The top corporate rate and the treatment of pass-through income can affect business owners differently from wage earners.
- Are retirements taxed by the state? Some retirement income may receive exemptions or partial exemptions. The impact varies by source and level of federal-adjusted gross income.
- Will there be changes in 2026? Yes. The 2026 session updated rules in income, corporate, and administration areas, with changes aimed at simplification and targeted relief for specific groups within the Connecticut state tax framework.
- How can I estimate my Connecticut tax? Use a state-specific calculator or worksheet that inputs your wages, deductions, credits, and any pass-through income. Start with your expected filing status and standard deduction amounts.
Conclusion
Connecticut’s tax landscape in 2026 blends an ongoing progressive income tax with local charges that shape what households and businesses actually pay. The total burden depends on earnings, family structure, and where you live or operate.
Key takeaways to guide planning:
- The income tax uses multiple brackets, so small increases in earnings can push portions into higher rates while other portions stay taxed at lower levels.
- Sales and property taxes remain major components of the total burden, and local differences can change bills for both homeowners and shoppers.
- Business owners should consider corporate taxes and pass-through rules, which can shift how income is taxed at the state level.
- Legislative changes may affect deductions, tax credits, and administration, so verify current Connecticut state tax rules when you file your tax return and review planning assumptions each year.
For households and firms, a practical approach is to estimate the total tax load using year-specific inputs for wages, deductions, and credits, then compare scenarios. A careful review of filing status, exemptions, and local rates helps prevent surprises at year end.