Budgeting and saving
Budgeting and saving are essential skills for anyone running or participating in a virtual business. This guide offers practical steps to manage income and expenses, so you can build savings, cover unexpected costs, and stay aligned with your financial goals.
What this covers
This guide highlights the core aspects of personal finance for virtual ventures:
- Tracking and classifying cost and revenue streams with real examples, such as a freelance designer logging client invoices and software subscriptions
- Setting up a realistic budget and saving plan, including a 3‑month expense cushion
- Debt management and emergency fund concepts, plus how to choose between a high‑yield savings account or a money market fund
- Tools and templates for quick cash-flow checks, like a simple weekly spreadsheet and a mobile app reminder system
Why budgeting and saving matter in virtual business contexts
In a month to month world, income and expense can swing with client demand. A practical budgeting routine helps you:
- Keep net income stable by planning for variable expenses like platform fees, hosting, and contractor costs
- Fund retirement and long‑term goals while preparing for emergencies, such as building a sinking fund of 3, 6 months of expenses
- Reduce stress when medical bills or major repairs pop up by having a quick‑access emergency line of credit or a cash buffer
Track and categorize expenses
Tracking and organizing your costs is the first step to a clear budget for a virtual business. Start by separating what stays the same from what can change each month, so you see where your money goes and where you can save. For example, if you run a remote coaching service, your platform fee might be fixed while client outreach costs vary with promotions.
Fixed vs. variable expenses
Fixed expenses stay the same each period, like rent for a workspace or a monthly software subscription. Variable expenses rise and fall, such as advertising costs or client incentives. At tax time, you can apply a simple rule: if you can predict it within ±20%, treat it as variable.
- Fixed examples: monthly hosting, insurance, essential software, recurring memberships.
- Variable examples: freelance labor, marketing campaigns, travel for client meetings, utilities driven by use.
Knowing the split helps you plan for months with fewer sales and seasons with heavier activity. It also guides how you set aside money for savings and emergencies. Practical step: earmark 3, 6 months of fixed costs in a separate rainy-day fund.
Common virtual-business costs to monitor
Keep a running list of typical expense categories you will regularly face in a virtual business. Create a simple dashboard that updates weekly so you can spot spikes early.
| Cost category | Why it matters | How to track |
|---|---|---|
| Software subscriptions | Essential tools can sneak up in price | Monitor monthly charges and renewal dates |
| Payment processing | Fees cut into net income | Record per transaction, average fee per sale |
| Marketing and ads | Direct link to revenue but easy to overspend | Set caps by campaign and compare ROI |
| Freelance labor | Variable but necessary for growth | Track hours, rate, and project status |
| Hosting and data storage | Supports online presence and data safety | Review usage and billing quarterly |
Regularly categorize new costs as fixed or variable and note any changes month to month. This keeps your budget plan accurate and prevents overspending in busy periods. If a category shifts from fixed to variable after a product launch, update your forecast accordingly.
Create a practical budget framework
Choosing a budgeting method
Different budgeting methods help you manage money in a virtual business. Pick one that fits how you earn and your discipline, then test it for a few months with real numbers.
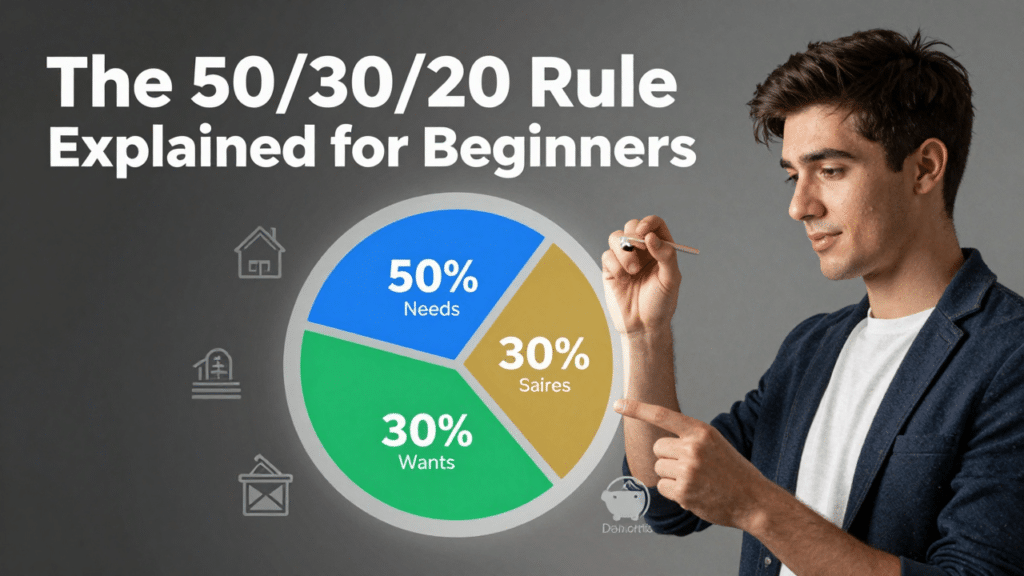
- 50/30/20 assigns 50% to needs, 30% to wants, and 20% to savings or debt payoff. Example: on a $4,000 month, $2,000 goes to essentials, $1,200 to discretionary spending, and $800 to savings or debt reduction.
- Zero-based plans every dollar’s job so income minus spending equals zero at month end. If you earn $5,500, you assign every dollar to a category before you spend.
- Envelope uses envelopes for each category, limiting cash on hand or card usage. For instance, cap software at $180 and marketing at $250 per month.
In practice, choose a method you can actually follow for 3 consecutive months. If income is unpredictable, zero-based or envelope can help you adapt to lean periods and irregular cash flow.
Setting realistic spending limits for each category
Start with a conservative baseline for essentials and adjust as you learn patterns.
- List categories like rent, software, hosting, marketing, client payments, taxes, and quarterly fees.
- Assign a monthly cap to each based on past activity and forecasted revenue. Use historical averages and add a 5, 10% cushion for surprises.
- Keep a small cushion for unexpected costs to prevent rushing into debt. For example, set aside an extra $100, $300 monthly for unplanned expenses.
Review caps after 1, 2 months and adjust them based on actual results. This keeps your budget aligned with real performance and helps prevent overspending.
Automate and optimize savings
Automating savings helps you grow your money without constant effort. A simple rule is to move a portion of earnings to a savings account right after you get paid. This reduces the chance you spend it elsewhere and keeps your financial goals on track.
Automating transfers to savings accounts
Set up automatic transfers on the day you receive a paycheck or at a fixed date each month. Start small if needed and increase as expenses grow or revenue rises. For example, if you earn $4,000 a month, begin with $200 and raise to $400 after three months.
- Link your checking and savings accounts for quick transfers.
- Choose a predictable amount, such as 5, 15% of earnings, and adjust with income changes.
- Automate all types of savings, including an emergency fund and goal-specific accounts.
This one-step habit compounds over time and reduces the chance of late transfers or skipped savings. It also keeps your mental budget clear since money moves before you see it.
Building a virtual emergency fund and short-term goals
Use a separate virtual fund to cover unexpected costs like software outages or supply delays. A practical target is to accumulate 1, 3 months of essential expenses.
- Set monthly targets for short-term goals such as equipment upgrades or marketing experiments.
- Allocate toward each goal with clear deadlines and a capped amount each month.
- Review progress quarterly and reallocate if plans shift or new priorities appear.
Regularly refreshing the short-term plan keeps the savings aligned with your current needs and income flow.
Implement debt management tactics
Prioritizing high-interest debt
High-interest debt costs you more over time. Start by listing all debts with their interest rates and minimum payments, then focus extra payments on the highest rate first. This approach lowers the total amount paid and speeds up repayment.
- Rank debts by APR.
- Make minimum payments on all but the top item.
- Apply any extra funds to the highest APR debt until it is paid off, then move to the next.
Real-world example: if you have a 22% credit card, a 9% student loan, and a 7% car loan, target the card first. If you can add $200 monthly, that extra goes to the card until it’s cleared, then you sweep to the next highest rate.
Strategies for virtual-business loans and credit lines
Credit lines and small loans can help when cash flow is tight, but they add cost. Use them strategically and keep a clear payoff plan to avoid debt spirals.
- Compare total cost, not just the monthly payment, to understand true debt load.
- Limit new borrowings to projects with predictable revenue and a clear path to repayment.
set a quarterly limit on outstanding balance and schedule automatic alerts if it nears that cap. For example, if you borrow for a marketing campaign, calculate expected lift and margin; stop borrowing if projected monthly revenue does not cover interest and principal within 12 months.
- Schedule regular reviews of balance, rate, and usage to prevent overborrowing.
Build a Personal Finance Toolkit for Virtual Businesses
A focused toolkit helps you stay on top of money in a virtual business. It should combine ready made templates and quick calculators to track income, expenses, and cash flow without fuss. This section covers two practical subtopics you can start using today.
Budgeting templates and simple calculators
Use templates to organize income, fixed costs, and variable spending. Create separate sheets for different revenue streams like services, digital products, and affiliate income. Practical calculators can estimate monthly burn rate, break even point, and reserve targets with a couple of clicks.
- Budget template: list income sources, then itemize essential expenses and discretionary costs. Add a column for actuals each week to spot slippage early.
- Cash flow calculator: input expected receipts and outlays to see money left week by week. Use a row for unexpected costs and flag any shortfalls.
- Reserve target calculator: determine how many months of expenses you want in emergency funds, then test different scenarios for job slowdowns or platform changes.
Choose templates that are easy to customize as you add new products or adjust pricing. The goal is a quick view of where money comes from and where it goes, not a wall of numbers. Create a one page dashboard to review weekly trends in under 5 minutes.
Cash-flow projections for digital products and services
Forecasting cash flow helps you plan hiring, marketing, and inventory for virtual offerings. Build monthly projections from launches, include payment terms, and adjust for seasonality. For example, plan a big marketing push in Q3 if most sales occur in Q4.
- Estimate average lifetime value of a customer to price projects accurately. If LTV rises from $120 to $180, test a tiered pricing model.
- Schedule inflows by payment type and timing to spot gaps. Map out upfront deposits, mid month receipts, and late payments, then create reminders.
- Model scenarios to prepare for slow periods. Include a 10, 20% cushion for refunds or churn spikes.
Regularly compare projected vs actual results to refine assumptions and keep your budgeting realistic. This keeps the virtual business financially steady as revenue shifts. 💡 For example, if actual revenue runs 15% under projection for two straight months, investigate pricing, audience reach, or delivery costs and adjust quickly.
Habits for sustained financial health
Regular financial reviews
Set a monthly check date to review income, expenses, and progress toward goals. This keeps your budget alive and relevant for a virtual business. For example, if you launch a new service mid month, adjust the plan within 7 days to reflect the added revenue.
- Compare actuals to the plan and note 1, 2 variances to fix next month.
- Update savings targets if revenue shifts or new costs appear, such as rising hosting fees or freelance costs.
- Track debt payments to avoid missed payments and penalties, using calendar alerts a few days ahead.
Adjusting budgets with changing virtual income
Income in a virtual business can bounce month to month. Your budget should flex without breaking your core financial plan. If a client pays late, cancel nonessential ads for the month and reroute that cash to essentials.
- Shift discretionary spending first when earnings drop, leaving essential costs intact, like hosting, tools, and payroll for contractors.
- Increase savings if income rises, even by a small amount, to build resilience, such as setting aside 5, 10% of unexpected windfalls.
- Reassess long-term goals every quarter to reflect new revenue paths or markets, for example exploring a new niche or pricing tier.
| Practice | Why it matters | How to implement |
|---|---|---|
| Monthly reviews | Keeps money matters current | Set a calendar reminder; print a simple check sheet |
| Flexible allocations | Protects daily operations when income changes | Create a small, adjustable discretionary bucket |
FAQ
What is budgeting in personal finance? Budgeting means listing your income and expenses to see how much money you have left. It helps you save and avoid overspending in a virtual business. For real results, set a monthly target, review weekly, and adjust as needed.
- How do I start a simple budget plan? Start with after-tax income, list fixed and variable costs, then set small saving money goals for the month. Example: if you earn $3,000 after tax, aim to save $300 first month, then increase by $50 each month.
- What counts as essential expenses? Rent, utilities, food, healthcare, and any recurring payments you must make to keep operations running. Add a weekly grocery cap and set a baseline for utilities to catch leaks early.
- Should I use a budgeting tool or manual tracking? A budgeting tool can automate cash-flow projections, but a simple template works if you prefer bank style control and transparency. Try a hybrid: auto-track income, manual review for discretionary spend.
How much should I save each month? A practical target is to put aside a savings amount that covers 1, 3 months of essential expenses, then grow it to cover longer-term goals like emergency needs or planned retirement contributions. For a $2,500 monthly outlay, aim for $2,500, $7,500 in an emergency fund within 6, 12 months.
What if my virtual business revenue fluctuates? Build a flexible plan with a small reserve and adjust discretionary spend first when income falls, keeping essential costs covered. Add a quarterly review to reallocate funds after seasonality spikes.
Conclusion
Budgeting and saving for a virtual business isn’t about doomscrolling numbers. It’s about a simple, repeatable system that fits how you earn and spend online. Start with a realistic budget that mirrors your income and track the big costs you face each month.
By now you should have a clear plan to save, manage debt, and keep emergency funds in good shape. Your toolkit can be small but focused: a budgeting tool, a basic savings account, and a calendar reminder for monthly reviews. Consistency beats perfect timing when building financial resilience.
- Review results every month and adjust based on changes in revenue, such as a new client or a seasonal spike.
- Prioritize essential expenses like hosting, payment processing fees, and taxes, and cut spend when revenue dips, for example by pausing nonessential ads.
- Keep long-term goals in sight while staying flexible for shifts in the source of income, such as adding a freelance side project to smooth cash flow.