Why investing matters
Investing helps your money grow beyond what a savings account can offer. By putting money into investment products like stocks or bonds, you aim to beat inflation and build wealth over time. The key is a plan you can stick to, not quick wins; focus on your long-term investment goals.
What you’ll learn
You’ll get practical guidance on setting goals, building a safe financial foundation, choosing a simple approach, and staying focused during market ups and downs.
Assessing your current financial foundation
Before you invest, check these basics:
- Emergency fund: have 3 to 6 months of living expenses ready in a savings account to safeguard against unexpected events while you’re investing.
- High-interest debt: plan to pay it off or refinance if possible to protect your hard-earned money.
- Regular contributions: set a small, recurring amount you can commit each month
Define your investment goals
Short-term vs. long-term goals
Choose two or three clear goals you want to reach with investing. Short-term goals are usually 1, 3 years, like saving for travel or a down payment. Long-term goals stretch from 5 to 30 years, such as retirement or funding a child’s education, and the earlier you start, the more you can benefit from compounding. Having both timelines helps you pick the right mix of securities and the pace of contributions.
- Short-term examples: vacation fund, building an emergency buffer up to 6 months of expenses
- Long-term examples: retirement, college savings, buying a home
Time horizon and expected milestones
Link each goal to a target date and a milestone you can track to assess your rate of return as you choose to invest. For example, a $10,000 goal in 3 years could be broken into quarterly checkpoints. Your time horizon guides how you set risk and how aggressively you invest.
- Actionable milestone: save a portion of the target each year
- Review point: check progress every 6, 12 months
Aligning goals with risk tolerance
Understand how you feel about market swings. Far-future goals can tolerate more volatility, while near-term aims usually need steadier growth in your investment portfolio. Let your risk tolerance shape your asset mix and how you rebalance over time.
- Keep a conservative tilt for near-term aims
- Use a balanced investment strategy for mid-term goals.
- Consider a growth-oriented mix for longer horizons
Build a simple financial foundation
Before you start investing, lock in the basics that keep you steady. A solid foundation of diversified securities reduces risk and makes your invested money work harder over time, especially when you begin investing early to maximize your net worth. Here’s how to build it without overcomplicating things: open an account and start investing today.
Emergency fund essentials
An emergency fund acts as a buffer for unexpected costs and helps you avoid dipping into investments during market drops. Aim to cover several months of essential living expenses in an accessible account.
- Target: 3-6 months of essentials as a starting point
- Location: a savings account at a bank or credit union that is federally insured
- Accessibility: keep funds liquid so you can access them quickly when life throws a curveball, which is crucial when you need a lot of money.
Managing high-interest debt
High-interest debt can erode the value of your investment from any investment strategy. Tackle this first so your returns aren’t eaten away by interest charges, allowing you to set money aside for future investments.
- Prioritize paying off credit card debt before investing if rates are high
- Consider a low-interest loan refi only if it meaningfully lowers costs
- Maintain minimums on essential payments while allocating extra toward the highest-rate balance to maximize your net worth.
Budgeting for consistent investing contributions
Small, regular contributions beat big one-off deposits. A simple budget helps you commit and grow over time.
- Set a realistic monthly amount you can invest without skipping
- Automate transfers to a basic investment account or fund
- Review your plan quarterly to adjust for income changes or expenses and ensure you’re investing wisely.
Choose an investment approach: index funds and ETFs
What are index funds and ETFs
Index funds are a great way to invest for beginners. are passively managed and track a market index, like the S&P 500. ETFs, or exchange traded funds, are similar but trade on an exchange like stocks. Both provide broad exposure with typically lower costs than active funds.
- Low expense ratios compared to many active funds
- Broad market exposure reduces company-specific risk
- Simple way To build a diversified core portfolio, you need to invest in a variety of asset classes.
Why diversification reduces risk
Diversification spreads money across different assets so a single poor performer won’t derail your plan. Combining mutual fund and bond index funds helps smooth volatility over time.
- Diversifying across sectors, regions, and asset classes is a key investing strategy.
- Less exposure to a single company or industry shock
- Helpful for long-term savers who want steady growth in their retirement savings.
How to start with dollar-cost averaging
Dollar-cost averaging is a way to invest by committing a fixed amount on a regular schedule, regardless of market moves. This investing strategy reduces the risk of trying to time the market and builds discipline for those who want to invest but are new to investing.
- Example: invest $200 monthly into a total market index fund
- Automatically schedule transfers to your investment account
- Reassess contributions annually as income changes
Understand account types and tax implications
They are suitable for money you might need before retirement, particularly in a money market account. The goal is to balance tax advantages with liquidity and access to funds while supporting your investment plan.
Tax-advantaged accounts
Tax-advantaged accounts can help you keep more of what you earn, but they come with rules. Common options include Roth and traditional accounts, each with different tax treatments and limits.
- Roth accountsContributions to a retirement plan are after tax, and qualified withdrawals are tax free in retirement.
- Traditional accounts can be a suitable investment product for long-term savings.Contributions may be tax deductible now, earnings grow tax deferred, withdrawals are taxed as ordinary income later, which is beneficial for your retirement savings.
- Eligibility and limits vary by account type and income, so verify current rules before contributing.
Taxable brokerage accounts
Taxable accounts offer flexibility and no early withdrawal penalties, but you pay taxes on earnings annually or when you sell your investment choices. They are suitable for money you might need before retirement.
- Capital gains tax applies when you sell at a profit, with rates depending on holding period.
- Dividends may be taxed in the year you receive them, at ordinary or qualified rates.
- No annual contribution limits, but taxes reduce net returns over time.
Contribution limits and withdrawal rules
Understand how much you can put in each account and when you can take it out without penalties. This prevents surprises and protects your plan, ensuring you do not lose money unexpectedly.
| Choosing the right account type affects how you save, grow, and withdraw money from your investment products. | Annual limits | Understanding withdrawal rules is essential when saving and investing. |
|---|---|---|
| Roth | Depends on income | Qualified withdrawals after age 59½, after meeting the five-year rule |
| Traditional | Contribution limits apply per year for your retirement savings. | Taxes due on withdrawals in retirement; early withdrawals may incur penalties |
| Taxable brokerage | No set limit on how much you choose to invest each year. | No penalties for withdrawals; however, there are taxes on gains and dividends that can affect the value of your investment, which is important to consider when you need to start investing. |
Build your first portfolio: a sample starter mix
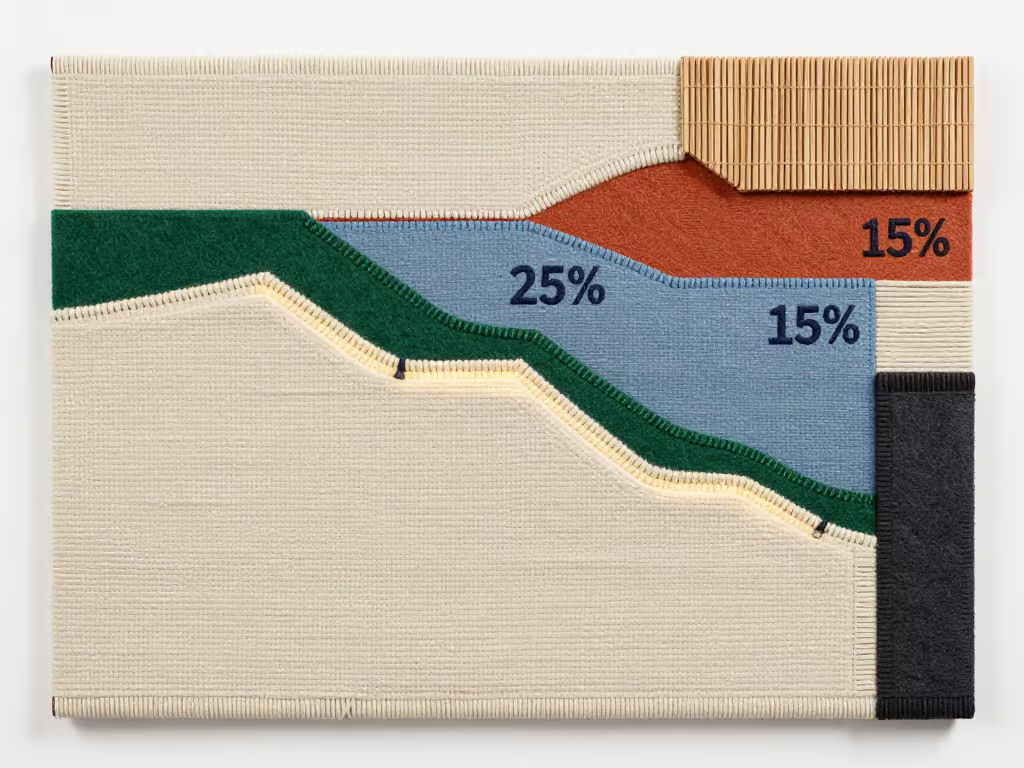
Starting simple helps you learn without overcomplicating things. A practical starter mix can grow with you while keeping risk reasonable and costs low.
Core holdings for beginners
Begin with a few broad, low-cost funds that cover the market. A straightforward starter could look like:
- 60% total stock market index fund or ETF for broad equity exposure
- A minimum investment of 25% of your income can set a strong foundation for your portfolio. global or international stock fund for diversification outside the U.S.
- 15% Consider a bond fund or bond ETF to dampen volatility and enhance your investment returns.
Adjust percentages based on your risk tolerance. If you want less risk, tilt toward bonds; if you’re comfortable with more volatility, increase stocks.
Rebalancing basics
Rebalancing keeps your original targets intact. Do it at regular intervals and after big moves in the market to take advantage of potential investment returns.
- Review every 12 months or after a 5, 10% swing in asset weights
- Sell portions that have grown too large and buy those that have shrunk to align with your investing goals, ensuring the money you invest is effectively managed.
- Keep costs low by using automatic contributions and default settings
Adjusting the mix as you gain experience
Your comfort level and investing goals change over time. Update the investing strategy when you hit new milestones, such as a longer time horizon or larger savings to better align with the risk you’re willing to take.
- Toward retirement: increase bond allocation gradually
- Need more growth: raise stock exposure modestly to get started with investing.
- Prefer simplicity: consider a single all-in-one fund that matches your risk
Learn about risk and diversification
Asset allocation concepts
Asset allocation helps you spread money across different asset types to manage risk. Your mix should align with how long you plan to invest, how much risk you can tolerate, and your financial goals. For example, a 25 year old with a long horizon may favor more stock, while someone near retirement might tilt toward bonds.
- Time horizon influences risk tolerance: longer horizons can weather more volatility.
- Risk tolerance guides your target mix between stocks, bonds, and cash equivalents.
- Starting simple with a core allocation helps you avoid overcomplicating the plan, especially when you are ready to start investing.
Diversification across asset classes
Diversification means not putting all your money into one asset. It aims to smooth returns by including different asset classes that behave differently in market conditions. A practical starting point is a core mix that covers U.S. stocks, international stocks, and bonds to create a balanced investment portfolio. The goal is to reduce the chance that a single event dramatically harms the whole portfolio, ensuring your financial future remains secure and optimizing your annual rate of return.
- Stocks offer growth but can swing a lot in the short term.
- Bonds provide income and typically lower volatility.
- Cash or cash equivalents act as a safety buffer for liquidity needs.
Recognizing and avoiding common pitfalls
New investors often chase the latest fad or pile into one asset type. Staying within a planned allocation helps prevent big swings in value. Watch for these mistakes and how to avoid them:
- Overusing single-country bets: diversify beyond one market or region.
- High turnover: frequent trading increases costs and taxes, with unclear benefits.
- Ignoring fees: even small expense differences can compound into meaningful gaps over time.
Set up your investing process
Having a repeatable investment strategy helps you invest with intention and avoid emotional decisions. You’ll build wealth faster when your money goes in regularly, your plan gets reviewed, and you stay the course during ups and downs in your investment decisions.
Regular investment cadence
Automate whenever possible. Set up monthly contributions to your chosen investment account so you buy consistently, no matter what the market does. A simple rule: contribute a fixed amount each month, then increase as your income grows.
- Use automatic transfers to your account after each paycheck
- Keep a steady schedule instead of timing the market
- Start small if needed with a money market fund and scale up as you can.
Review and adjust strategy annually
Once a year, reassess your goals, risk tolerance, and life changes. If you’ve reached a milestone or your time horizon shifts, adjust your asset mix and contribution levels accordingly.
- Check progress toward your investment goal
- Update the target allocation if plans or risk tolerance shift
- Revisit fees and account options to keep costs low
Stick to your plan during market volatility
Volatility tests discipline. Do not abandon your plan after a drop or chase hot picks after a rally; instead, stick to your investment choices. Remind yourself of your long-term horizon and the value of cost-effective, diversified holdings in your retirement plan to ensure you need to invest wisely.
- Avoid selling in a panic unless your plan calls for it; remember, it’s important to manage your level of risk.
- Consider rebalancing your investment strategy if allocations drift beyond set thresholds.
- Document decisions to prevent repeated mistakes
FAQ
What should I invest in first as a beginner?
Start with broad, diversified options. A simple way to invest is to choose low-cost index funds or ETFs that track the overall market. This gives you instant diversification without needing to pick single stocks.
- Consider a core stock fund for growth and a bond fund for stability in your long-term investment strategy.
- Look for funds with low expense ratios to keep costs down over time.
- Keep a long‑term focus to ride out short‑term volatility.
Is $100 enough to start investing?
Yes, you can begin with $100, but choose accounts and products that support small contributions. Robo-advisors or fractional shares make this practical, letting you build a starter portfolio without a large upfront investment.
- Check for any minimums or custodian fees that could eat into your saving and investing efforts, especially if you’re saving for your children’s future.
- Automate small monthly contributions to grow gradually.
- Reinvest any growth to compound over time, as this is the time to start investing for your future.
How long before I see returns?
Expect a long horizon for meaningful returns on the money you invest. Stocks have historically shown growth over years, not days or weeks, while bonds can provide steadier, shorter-term income. Your timeline should align with your goal schedule.
Conclusion
Recap of starter steps
Define a goal with a realistic time frame, build a basic safety net, and choose a simple, low-cost approach like index funds or ETFs. Set up automatic contributions to keep momentum without chasing market timing, which can help you start saving consistently.
Next steps for continued learning
Review progress annually, adjust for life changes, and tighten your plan as you gain experience. Consider revisiting asset allocation concepts and practicing rebalancing with an investment professional to stay aligned with your risk level.
Encouragement for starting today
Even a small, regular contribution compounds over time. Set up a simple recurring plan now and increase contributions as you can to enhance your saving for your children’s education. Waiting for perfect timing can cost you steady growth.