What Are the Best Ways to Borrow Money?
Personal loans
A personal loan is a fixed amount you borrow and pay back in regular installments. They often have lower emergency loan rates than high‑interest options and predictable monthly payments. Typical loan terms range from 12 to 60 months. Lenders review your credit score and credit report to decide the best option for an emergency loan with bad credit. loan approval and loan amount.
Installment loans
Installment loans spread repayment over time, not just at a single due date. They can be secured or unsecured and come with a clear loan agreement. Look at the loan term and total cost of borrowing, not just the monthly payment, to avoid surprises.
Cash advance loans
A cash advance loan gives cash quickly against a credit line or card. They often carry higher emergency loan rates And fees, so use them only for urgent needs, especially for borrowers with bad credit. Be mindful of the minimum credit score requirement and potential impact on your credit profile.
Payday loans
Payday loans are small, short‑term loans due on your next paycheck. They can be fast to get, but come with very high costs per type of loan. loan funds. If you’re weighing this, compare the APR and origination fee against alternatives.
Borrowing money apps
Borrowing apps offer quick online loans or cash advances. They’re convenient but check for soft credit inquiry versus hard pulls, fees, and repayment methods. Always review the loan terms and make sure you can handle the monthly payment.
How can you borrow money fast?
Instant personal loans
These are marketed for speed, often with a same-day decision. Typical steps: apply online, a soft credit check, and a quick approval decision. If approved, funds may arrive the same day or within 1, 2 business days. 🕒
Same-day loans online
These aim to cut delays. You usually fill a short application, show some income evidence, and the lender decides after either a soft or hard inquiry. If you meet criteria, funds can come by the end of the business day. 💨
Same-day cash advances
Cash advances draw a cash amount from a credit line or card. They often carry higher fees and can impact your credit if used frequently. Always read the terms before accepting funds. 💳
Instant payday loans online
Instant payday loans online offer quick access to a small sum tied to your next paycheck. They can be convenient but tend to come with high costs and a tight repayment window. If you’re weighing them, compare APR and origination fees with other options. ⚖️
How to borrow money with bad credit
Borrowing with a low credit score
If your credit score is low, you still have options, but costs can be higher. A credit score impact shows up in interest rates, fees, and your loan approval chances. Start with lenders that report to major credit bureaus to help rebuild your credit profile with on-time payments. 💳
- Compare soft credit inquiry checks first to avoid dinging your score during the initial look.
- Ask about a secured loan option to lower risk for the lender and your rate.
- Set a monthly payment you can afford and use a loan calculator to project total cost.
No-credit-check loans
No‑credit-check loans can sound tempting, but they often come with steep costs or unclear terms. Always verify the loan terms and read the loan agreement for any hidden fees. ⚠️
- Look for explicit disclosures on origination fees and early repayment policies.
- Prefer lenders offering loan funds within 1-3 business days when possible.
- Be wary of lenders making guarantees without a documented credit report check.
Small loans with no credit check
Small loans with no credit check can fill urgent needs, but they may come with higher emergency loan rates and strict repayment windows. Compare the loan amount to your budget and confirm the total cost before borrowing. 💡
- Check how the monthly payment fits your budget and avoid rolling over debt.
- Opt for lenders with transparent loan terms and a clear loan agreement.
- Ensure you can provide steady income documentation if requested to support income verification.
Alternatives for bad-credit borrowers
Before locking in a loan, consider safer routes that protect your finances. Alternatives can reduce risk and still help when money is tight. 🧭
- Ask a credit union for a small secured personal loan with more favorable terms than standard online loans.
- Request a payment plan from a utility or service provider to spread costs.
- Explore a line of credit with a predictable monthly payment and established repayment rules.
| Option | Typical risk | Best for people with less-than-perfect credit history looking for flexible borrowing options. |
|---|---|---|
| Secured personal loan | Lower risk for lender, possible collateral | Building credit with manageable payments |
| No-credit-check loan | Higher costs, fewer protections | Urgent, small sums when other options fail |
| Credit union loan | Membership required, often better rates | Stable terms, supportive lender |
Can you borrow money without a job?
Yes, you can borrow without a traditional job, but the options and costs shift. Lenders focus on what you can repay and your overall financial picture, not just employment. 🧭
What lenders may accept as income
Income sources vary by lender, but common ones include:
- Social security benefits, disability payments, or pension
- Alimony, child support, or rental income
- Investment income or dividends
- Non employment earnings with documented history, such as freelance work
Some lenders may require proof such as bank statements or a statement of expected income. A soft credit check can help you see offers without a hard pull. 💳
Why ability to repay matters
Repayment depends on stable cash flow outside a job. Useful checks include:
- Regular deposits to your bank account
- Steady inflows from benefits or investments
- A clear monthly budget showing obligations and leftover funds
Higher risk means higher costs or stricter terms for borrowers with bad credit. Expect higher interest or smaller loan amounts. 🔎
Risks of borrowing without stable income
Loans without solid income can backfire. Watch for:
- Very high APRs that drain finances
- Short repayment windows during uneven cash flow
- Aggressive collection practices or renewal pitches
Always compare terms, fees, and total costs before accepting anything. A clear plan helps avoid surprise payments. ⚠️
How to borrow money before payday
Payday advances
Payday advances let you access a small amount of cash before your paycheck. They’re quick, but the cost can be high if you don’t repay on time. 💸
- Typical loan amounts: a few hundred dollars
- Repayment: usually with your next paycheck
- Fees: often higher than standard loans
Cash advance apps
Cash advance apps let you borrow from your phone with fast access to funds. They’re convenient, but the total cost can add up, so compare terms first to ensure you get the best deal on the money you need. 📱
- Common fees: small flat fees or a percentage of the advance
- Repayment: pulled from your next direct deposit or bank transfer
- Approval: may rely on income and spending patterns
Short-Term installment loans
Short-term installment loans spread the repayment over several weeks to a few months. They usually cost less than payday loans and require a plan to repay. 🗓️
- Loan terms: 2, 12 months often available
- Repayment: fixed monthly payments
- Loan amounts: larger than advances, but still not huge
Lower-cost alternatives
Before you borrow, explore cheaper options that protect your budget. 🧭
- Ask a credit union for a small, low-rate loan with friendly terms
- Negotiate a payment extension with a lender for upcoming bills
- Use a zero-interest promotional period if offered by a card or lender, then plan repayment
| option | typical cost | best for |
|---|---|---|
| Payday advances | High fees, quick cash | Emergency, small amount needed fast |
| Cash advance apps | Moderate fees, fast access | When you need funds today |
| Short-term installment loans | Lower cost than payday, longer term | Smaller, planned purchases |
| Lower-cost alternatives | Lowest cost potential | Better long-term payoff and budgeting |
How to find a low-interest loan
To get the cheapest loan, focus on the total cost, not just the rate. A loan with a slightly higher rate can end up cheaper if it has longer terms or lower fees. Here’s how to approach it step by step. 💡
Compare APR, not just the interest rate
APR combines the interest rate with fees, origination costs, and other charges. A loan with an 8% rate but high fees can cost more than a 10% rate with lower fees, particularly for those with less-than-perfect credit. Always read the full APR to see the real cost over the term. 📊
Compare multiple lenders
Shop at least 3-5 lenders to spot price differences and different terms. Different lenders may favor different credit profiles, so you might find a good fit with a credit union, online lender, or bank. 🏦
Check the loan term
Longer terms reduce monthly payments but raise total interest paid. Shorter terms save interest but require bigger monthly payments. Pick a term that fits your budget and still keeps total costs low. ⏳
Improve your chances of getting a better rate
- Improve credit profile modestly before applying, if possible
- Keep credit utilization low and avoid opening many accounts at once
- Choose a loan with a soft credit inquiry to see offers without affecting your score
How personal loans work
Personal loans are a straightforward way to borrow a fixed amount with predictable monthly payments. You apply, a lender reviews your credit, and if approved you get loan funds deposited to your bank. 🏦
Personal loan eligibility
Eligibility depends on your credit score, income, and debt load. Lenders look at your credit report and verify income with bank statements. A soft credit inquiry may preview offers without hurting your score, helping you get approved for better terms. 💳
- Credit score needs vary, but a score of 580 or higher is common for some options
- Stable income helps your chances of loan approval
- Debt levels influence your monthly payments and approval decision
Easy personal loans vs fast personal loans
Easy personal loans focus on straightforward terms with clear repayment schedules, while fast loans emphasize speed of funding. Both require basic documentation, but speed can come with higher fees or shorter terms. ⚡
- Easy loans: longer terms, predictable payments, lower fees
- Fast loans: quicker funding, higher costs, tighter eligibility
- Both require a loan agreement outlining terms and repayment
How to choose a personal loan company
Choose a lender by comparing total cost, not just the rate. Look for transparent fees, repayment terms you can manage, and reliable customer service. 🧭
| Factor in your credit score when considering the type of loan you want to apply for. | What to check | Why it matters |
|---|---|---|
| APR | All-in cost including fees | Shows true long-term expense |
| Loan terms | Length of repayment | Affects monthly payment and total interest |
| Fees | Origination, prepayment, late | Can swing overall cost |
How quick installment loans work
Loan amounts and repayment
Installment loans come in smaller, predictable sums and are paid back in fixed monthly installments. Typical loan amounts range from a few hundred to a few thousand dollars, with repayment spread over 3 to 36 months, making them suitable for those looking to get an emergency loan. 💳
Each payment covers both principal and interest, plus any small fees baked into the loan terms. A longer repayment period lowers the monthly payment but raises total interest. Use a loan calculator to estimate the full cost over the term. 📈
Installment loans vs payday loans
When an installment loan may be more suitable
- You need more money than a quick cash advance but want to avoid a cash flow squeeze each payday.
- You prefer predictable payments and a clear payoff date.
- Your goal is to reduce overall borrowing costs compared with short-term, high-fee options.
How Borrowing money apps work
Borrowing money apps provide quick access to funds by linking to your bank and offering small loans or cash advances. They can speed up funding, sometimes in minutes, but they often cost more than traditional loans. 🕒
Eligibility requirements
Each app has its own rules, but common requirements include a valid bank account, a smartphone, and a minimum age. Some apps use soft checks to preview offers without harming your credit, while others may demand a higher score or steady income. 📱
- Typical income verification may be lightweight or skipped for small advances
- Past repayment history with the app can affect your limits
- Some apps restrict users with recent bankruptcies or collections when applying for an emergency loan with bad credit.
Common fees
Fees vary, especially for credit card cash advances compared to traditional loans. Always read the fine print before you accept an offer. Typical costs include explicit fees, interest on small balances, and occasional processing charges. 💡
- Origination or commitment fees charged upfront
- Interest if you carry a balance beyond a grace period
- Late or failed payment penalties in some cases
Repayment methods
Repayment is usually automatic from the linked bank account or a chosen card. Some apps let you repay early to save on interest, while others require a fixed schedule. 🧾
- Automatic withdrawals on due dates
- Manual payments via the app or web portal
- Flexible extensions in some cases, often with extra fees
What to check before using a borrowing app
Before you pick an app, compare total costs, speed of access, and protections. Look for transparent terms and a reputable lender profile. 🔎
| Check | What it means | Why it matters |
|---|---|---|
| APR and fees | All-in cost of borrowing | Direct impact on what you repay |
| Repayment terms | Length of the repayment window | Affects monthly cash flow |
| Creditor reputation | Reviews and licensing | Lower risk of scams or hidden charges |
What to check before borrowing money
Before you borrow, verify the true cost and the risk. Check the APR and all loan fees To avoid surprises when you repay your emergency loans for bad credit. Understanding the terms helps you pick the cheapest option and stay on track. 💡
APR
The APR shows the total annual cost of borrowing, not just the rate. It includes interest and fees, so a loan with a low rate can still cost more if fees are high. Compare APRs across lenders to find the best overall deal. 🧮
Loan fees
Look for any origination, prepayment, late, or processing fees. Even small upfront costs can add up over a short loan term. List all fees and add them to the loan total to see the real price. 💰
Repayment term
The repayment term is how long you have to repay. Longer terms reduce monthly payments but raise total interest. Short terms can save money but require bigger monthly bills. Use a loan calculator to compare. 📈
Lender reputation
Choose a lender with clear licensing and solid reviews. A reputable lender reduces the risk of hidden charges or pressure to borrow more, ensuring you can pay off your loan early if desired. Check customer feedback and verify licensing status. 🕵️♂️
Prepayment rules
Some loans charge penalties for paying off early. If you plan to repay ahead, confirm there are no prepayment penalties or that they’re reasonable. This affects how much you save by paying early. 🏁
Automatic withdrawal terms
Many lenders use automatic withdrawals. Ensure you know the due date, what happens if a payment fails, and any fees for failed attempts. Automatic plans should align with your cash flow. 🧾
Red flags to avoid when borrowing money
Watch out for signs that a lender might not be trustworthy or could trap you in costly terms. Spotting these red flags early helps you protect your finances and avoid bad deals. 🚩
Guaranteed approval claims
Any lender promising instant or guaranteed loan approval without a real check is a warning sign. Those offers often come with hidden costs or high interest. Always expect at least a basic review of your credit profile and income. 💡
- Promises of instant funding with no credit check
- Unclear requirements for eligibility
- Pressure to sign before you review the fine print
Upfront fees
Be wary of lenders asking for large upfront fees before any money is borrowed. Legit lenders may have small origination fees, but substantial upfront charges can be a trap. 🧾
- Large processing or activation fees before loan funds
- Fees that aren’t tied to a clearly defined loan offer
- Requesting payment before you see a contract
Unclear APR or loan costs
Always demand transparent pricing. If the total cost isn’t clear or the APR is buried in dense language, step back. You need to know the true yearly cost and all fees. 🧮
- Vague or missing APR disclosures
- Fees listed without a total cost calculation
- Complex terms that hide annualized costs
Pressure to borrow quickly
Rush can blind you to errors. If a lender pushes you to borrow now and skip time to compare, pause and review. Take at least 24 hours to read the contract. ⏳
- Limited time offers that push immediate sign‑ups
- Countdown timers used to urge fast decisions
- Requests to share sensitive data before consent
Unlicensed lenders
Only work with lenders that are properly licensed in your state or country. Unlicensed lenders may dodge consumer protections and vanish with your funds. 🔒
- No licensing information or verification
- Aliases or fake company addresses
- Suspicious disclosures about where funds come from
Unclear repayment terms
Repayment terms should be clear: how long, how much, and what happens if you miss a payment. If any part is vague, ask for a written, plain‑language explanation before you borrow. 🧾
- Unspecified due dates or payment amounts
- Penalties with unclear calculation methods
- Automatic withdrawals without clear fail‑safe options
How to compare borrowing options
Comparing options helps you find the lowest total cost and the best fit for your situation. Look beyond the monthly payment and focus on the full picture, including fees and terms. 💡
Personal loans
These are typically fixed, predictable loans from banks, credit unions, or online lenders. They usually involve a credit check and a solid credit profile. 🧾
- Fixed interest rate and term
- Often lower costs can be found in loans for bad credit. than payday options for good credit
- May require collateral in some cases
Installment loans
Repayments come in regular installments over several months. They can come from lenders or credit unions and vary in term length. 💳
- Structured repayment schedule
- May include origination fees
- Better for mid-range borrowing, especially for those seeking a payday alternative loan. than payday loans
Cash advances
Cash taken from a credit line or card, often with high fees and higher APR. Use only if you can repay quickly. 🏧
- High cost per dollar borrowed
- Immediate access to funds
- Impact on credit card limits
Payday loans
Small, short-term loans due at your next paycheck. They tend to carry very high fees and rates. ⚠️
- Fast access, minimal credit checks
- Very high cost of borrowing
- It’s easy to fall into debt cycles when relying on title loans.
Borrowing apps
Mobile apps offer quick cash with varying fees. Compare app terms, repayment windows, and any automatic withdrawals. 📱
- Often soft checks or no-credit-check options
- Fees and repayment terms vary greatly among lenders offering payday alternative loans. by app
- Watch for renewals or repeat borrowing traps
Credit union loans
Credit unions can offer lower rates and friendlier terms for members. Eligibility matters. 🏦
- Often lower APR than banks or lenders
- May require membership and structured approval
- Better service and flexible terms
| Borrowing option | Typical costs | Best for |
|---|---|---|
| Personal loans | Fixed rate, potential origination fee, and a complicated application process. | Larger, planned purchases |
| Installment loans | Interest + fees can significantly impact the total cost of money you need. | Steady repayments over time |
| Cash advances | High APR, fees | Fast access to cash |
| Payday loans | Very high fees | Short-term urgent needs may require you to get an emergency loan quickly. |
| Borrowing apps | Varies by app | Fast, small amounts |
| Credit union loans | Low APR, member-based | Affordable financing for members |
Before you apply: borrowing checklist
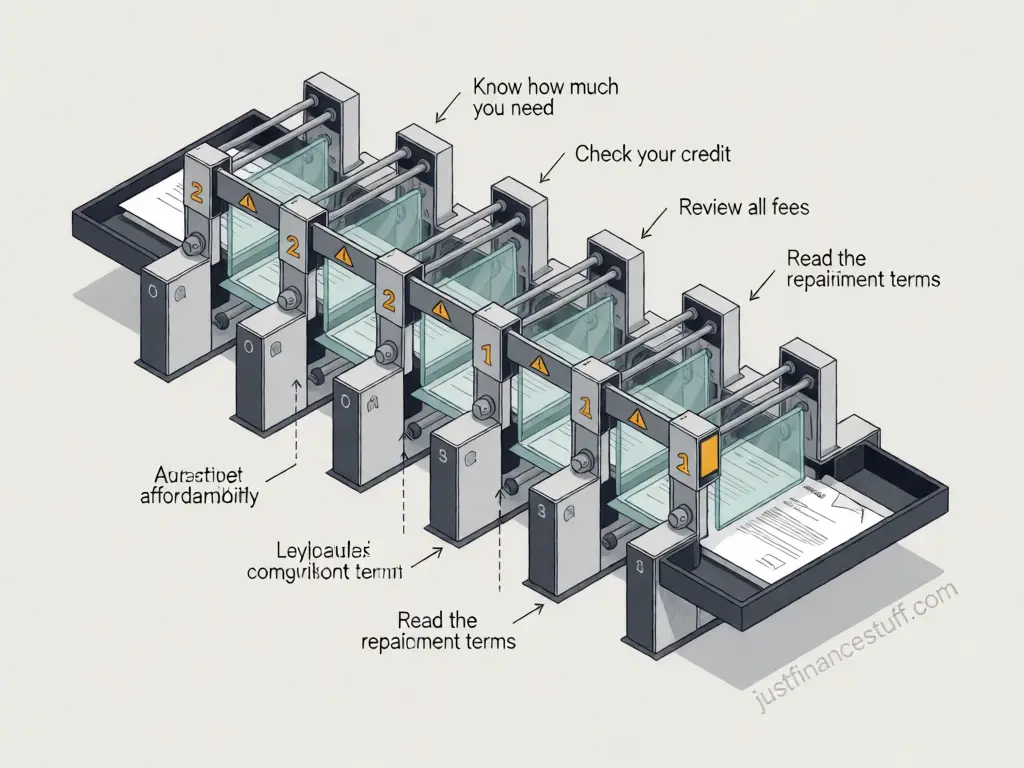
Know how much you need
Start with a precise loan amount. Borrowing more than you need adds unnecessary costs and complicates repayment. List exactly what the funds will cover and add a small cushion for emergencies. 💡
Calculate what you can afford
Make a quick budget to see monthly payment fits your income. A good rule is the loan payment should not exceed 15% of take-home pay. Use a simple loan calculator to test scenarios. 💰
Check your credit
Pull your credit report and review strengths and weaknesses. A clearer picture helps you pick realistic loan options and avoid surprises later. 🧾
Compare multiple lenders
- Bank, credit union, and online lenders
- Same or next-day funding vs delays
- Customer service and support quality
Compare APR and total repayment
Look at the annual percentage rate and how it adds up over the full term. A lower APR can save hundreds, even with a longer term. 🧮
Review all fees
Origination fees, late fees, and prepayment penalties change the bottom line. Ensure you understand every charge before signing. ⚠️
Verify the lender
Check licensing and read about their reputation. Avoid unlicensed or high-pressure offers that push you to borrow fast. 🕵️♀️
Read the repayment terms
Know due dates, automatic withdrawal rules, and what happens if you miss a payment. Get a written schedule and keep it handy. 🗓️
Frequently Asked Questions about borrowing money
Borrowing money can feel confusing. Here are clear, practical answers to common questions you’ll have when you compare options like a personal loan, installment loan, or cash advance. 💬
What is the difference between a loan and a credit line
A loan is a fixed amount you receive up front with set repayment terms. A line of credit acts like a spending limit you can borrow against, repay, and borrow again as needed. 🧭
What does a soft credit inquiry mean
Soft checks let lenders peek at your profile without affecting your credit score. A hard inquiry happens after you apply and can nudge your score down slightly. 🧐
How is the APR different from the interest rate
The interest rate is the annual cost for borrowing money. APR includes interest plus most fees, giving a fuller view of total cost. 🧮
Can I get a loan with bad credit
Yes, but options are limited and terms may be stricter. Look for lenders that offer products designed for limited or no credit history and compare costs carefully. 🔎
What should I check before signing
Review all terms, repayment deadlines, origination or prepayment fees, and any penalties for paying off early. Always read the agreement in full. 📝
Are there safer fast‑funding alternatives
Consider credit union loans or small, fixed‑rate installments from reputable lenders before opting for high‑cost options. 🏦
How do I improve my chances of approval
Have accurate income documentation, a steady payment history, and a realistic loan amount. A soft prequalification can help you estimate odds before you apply. 📄
Conclusion
Borrowing money can be handy in a pinch, but the real cost shows up in the loan terms, fees, and repayment schedule. If you need fast cash, start with options that balance speed with safety, especially when your credit is not perfect. 💡
Key takeaways to keep your finances on track:
- Prefer personal loans or installment loans with clear loan terms and predictable monthly payments over open-ended or ultra-high-cost options. 💳
- Compare APR and total repayment rather than just the upfront rate to avoid surprise costs. 🧾
- Check eligibility requirements, including the minimum fico score for people with bad credit. minimum credit score and required credit check, before applying. 🔎
- Be wary of no‑credit‑check or guaranteed approval promises; read the fine print on origination fees and repayment penalties. ⚠️
If you have bad credit, consider safer routes like a credit union loan or a small secured option that lowers risk for both you and the lender. 🏦